Fed rate hike will likely push borrowing costs on credit cards, mortgages — but benefit savers
Sep 16, 2026, 11:05 AM
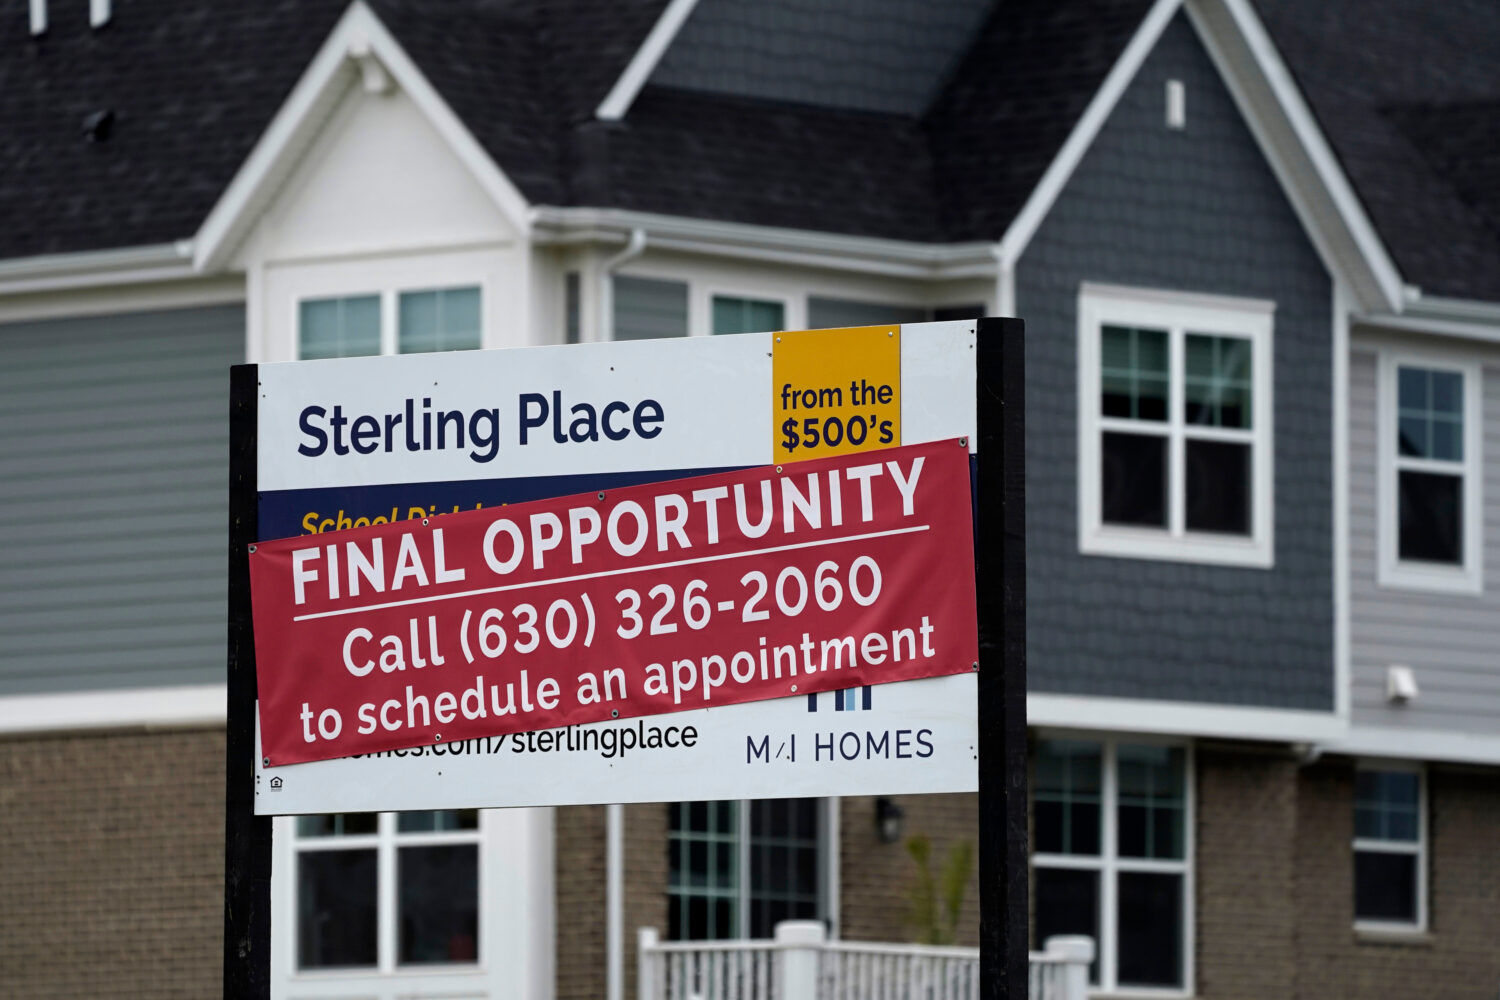
FILE - An advertising sign for building land stands in front of a new home construction site in Northbrook, Ill., on May 5, 2022. (AP Photo/Nam Y. Huh, File)
Credit: AP Photo/Nam Y. Huh
(AP Photo/Nam Y. Huh, File)

WASHINGTON (AP) — The Federal Reserve just raised the cost of money — bad news for borrowers, good news for savers.
The Fed increased its benchmark interest rate Wednesday by a quarter-point, the first rate hike since the summer of 2023. The hike will likely make it even costlier to borrow for homes, autos and other purchases. But if you’ve been socking money away, you’ll probably earn a bit more interest on your savings.
The increase boosts the Fed’s target rate to a range of 3.75% to 4.00%.
Here’s what to know:
The short answer: inflation.
Inflation has remained above the Fed’s 2% target for more than five years. The Labor Department reported Friday that consumer prices rose 3.4% in August compared to a year earlier, while the monthly increase quadrupled from July to hit 0.4%.
The Fed’s goal is to slow consumer and business spending by raising the cost of borrowing, thereby reducing demand for homes, cars and other goods and services, eventually cooling the economy and reducing upward pressure on prices.
Kevin Warsh, Fed chair since May, has assured Congress that central bank policymakers “have no tolerance for persistently elevated inflation.”
Anyone borrowing money to make a sizable purchase, such as a home, car or large appliance, will likely take a hit eventually. The new rate will also increase monthly payments and costs for any consumer who is already paying interest on credit card debt.
Then again, said Matt Schulz, chief consumer finance analyst at the online loan marketplace LendingTree, “the reality is that a single quarter-point rate increase isn’t really going to have a huge impact.” But it would be different if Wednesday’s hike marks the first in a series of rate increases. ”When this all becomes impactful to people is when you stack a few these on top of each other over time, and it adds up to something bigger,” Schulz said.
For now, U.S. household debt payments are relatively low overall as a percentage of after-tax income. So even if borrowing rates rise, many households might not feel a heavier debt burden immediately.
Most likely. Wednesday’s move probably means interest rates on savings accounts and certificates of deposit are headed higher. The Fed doesn’t set rates on savings accounts and CDs but it “sets the tone″ for them, the credit reporting agency Experian says. When the central bank started raising rates to combat an outbreak of inflation in March 2022, the average rate on a 1-year CD was stuck at a miserly 0.15%, according to FDIC data published by the Federal Reserve Bank of St. Louis. The rate shot up to 1.88% by September 2024 and has remained above 1.5% ever since. It was 1.71% last month.
Online banks and others that offer high-yield savings accounts typically compete aggressively for depositors. (The catch: They sometimes require significantly larger deposits.)
Mortgage rates don’t necessarily follow what the Fed does. At least not directly. They tend to track the yield on 10-year Treasury notes instead. Unfortunately for home shoppers, 10-year yields have been surging. On Monday they topped 5% for the first time since 2023 due to unease over surging energy prices and massive government debt that continues to grow. Treasury yields have continued to rise despite an intervention from the Treasury after Secretary Scott Bessent ordered the U.S. to buy back government bonds in a bid to push yields down.
The rate on the benchmark 30-year fixed-rate mortgage rose to 6.76% last week, the highest in more than 14 months, mortgage buyer Freddie Mac said.
The high cost of home loans is already taking a toll on the housing market. The Realtors association reported last week that sales of previously occupied U.S. homes dropped for the third straight month in August, growing at the slowest pace in more than a year.
Adjustable-rate mortgages could rise in order to price in a Fed hike. But many homeowners locked in low mortgage rates when COVID-19 slammed the economy and sent borrowing costs tumbling; so they are protected if mortgage rates rise in the wake of a Fed raTte hike. The National Association of Realtors reports that nearly half of mortgages outstanding are locked in at 4% or lower and almost a fifth were at 3% or lower in the first three months of 2026.
Most credit cards have variable interest rates that track the prime rate banks charge their best customers. And the prime rate responds quickly — within a month — when the Fed raises or lowers its benchmark “fed funds” rate, ”meaning that the Fed’s policy changes flow through to credit card rates rapidly,” researchers at the Boston Fed wrote in March.
Schulz at LendingTree reckons that most credit cardholders will see their rates rise by a quarter-point over the next couple of months.
Many Americans, coping with the high cost of living, are increasingly relying on credit cards to help maintain their spending. Total credit card balances hit $1.26 trillion in the second quarter — near the record $1.28 trillion set at the end of 2025 (though the numbers are not adjusted for inflation), according to the New York Fed.
The Fed indirectly influences auto loan rates by influencing the prime rate. Cars, especially new ones, are already prohibitively expensive. The average cost of a new car rose to $50,089 last month, according to Kelley Blue Book. The average loan rate last month was 7% for a new car and 10.6% for a used car, according to Edmunds. And the average monthly payment, Experian reported, was $765 in the second quarter of 2026.
“Most Americans are generally doing OK,” Schulz said. ”But it wouldn’t take a whole lot for them to not be doing OK. People’s financial margin for error is generally pretty small, and just the rising cost of most everything just squeezes them more and more.”
___