Takeaways from the AP’s analysis on the fundamental flaws in the national flood insurance program
Sep 29, 2026, 6:46 AM
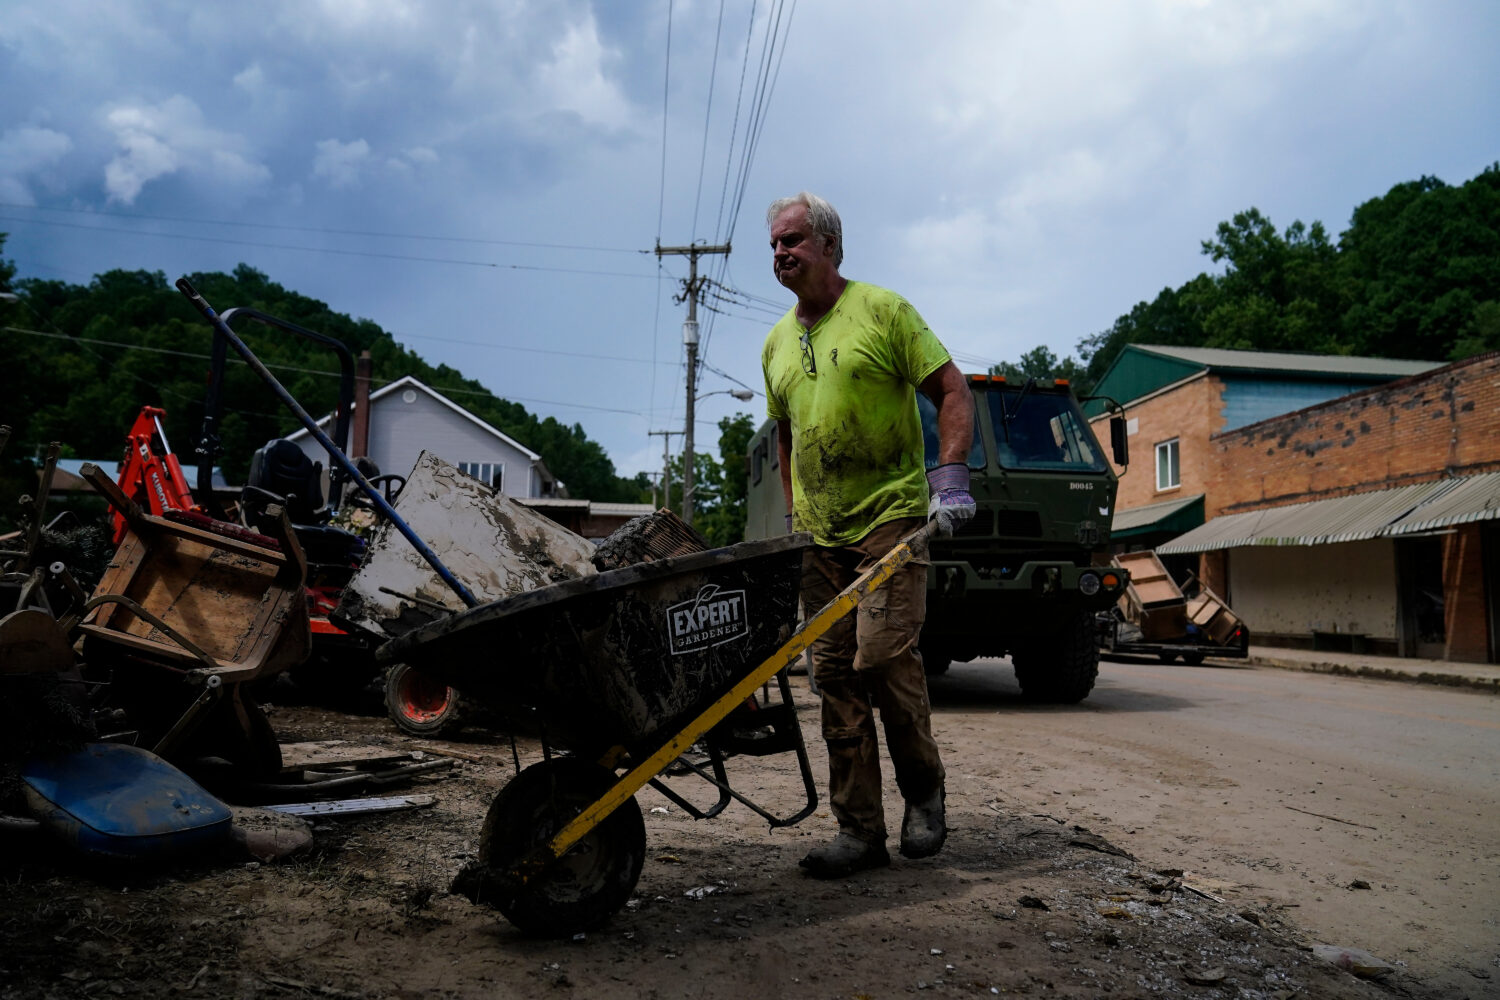
FILE - Jeff Hawkins helps clean his father's antique shop, called Curiosity Shop, Aug. 5, 2022, in Fleming-Neon, Ky., after massive flooding. (AP Photo/Brynn Anderson, File)
Credit: AP Photo/Brynn Anderson
(AP Photo/Brynn Anderson, File)

WASHINGTON (AP) — The nation’s flood insurance program struggles to balance affordability, flood protection and cost to taxpayers, leaving millions vulnerable at a time when climate change is driving flood risk higher.
Nationwide, just 2.4% of properties are covered by 4.5 million federal flood insurance policies, an Associated Press analysis shows — but 8.4% are at severe or extreme risk of flooding.
The problem is especially bad in eastern Kentucky — where in some ZIP codes, no more than 5% of properties are covered by flood insurance, even though hundreds or thousands of buildings are at extreme risk of flooding, according to figures from the federal government and data provided exclusively to the AP by the risk analysis group First Street.
It’s not just Appalachia — coastal areas, including parts of southern Louisiana, stand out, too. Areas at high risk of flooding and where few people are insured tend to be poorer, experts said, as are areas where FEMA’s flood maps don’t properly convey the severity of the risk or mandate that enough people buy coverage.
Here are the takeaways from the AP story:
Congress set up the National Flood Insurance Program in 1968. It offers flood insurance in participating communities that agree to take steps to manage flood risk, such as restricting construction in high-risk areas. Homeowners insurance doesn’t cover floods.
Policies are available to renters and businesses, but most are purchased by homeowners covering up to $250,000 for their property and $100,000 for belongings. FEMA flood maps determine who is in a high-risk area where flood insurance must be attached to a federally backed mortgage.
FEMA’s flood maps don’t do a good job of capturing the extent of severe flood risk. Millions think their homes are safer than they really are and aren’t forced to buy insurance when they probably should.
Consider the horrific 2022 floods in eastern Kentucky, when more than a foot of rain fell over parts of the state, killing more than 40 people.
Where the flood struck, just 2.1% of properties were insured then, a rate that remains about the same today, the AP analysis shows, even though about 47% are at severe or extreme risk of flooding. That’s a gap of 45 percentage points — more than 7 times the national average.
FEMA’s flood maps didn’t catch all that risk during the 2022 flood, with only 18% of the buildings that were affected falling within a high-risk zone.
Flood maps, which are commonly out of date, don’t consider some types of flood risk, such as flooding from inland heavy rains.
The places with the biggest insurance gaps are those where heavy precipitation flooding occurs away from large water bodies, said Jeremy Porter, the chief economist at First Street.
“That’s the Appalachian region, further inland, and then in the Midwest and Northeast in particular, extreme precipitation is the way climate change is manifesting itself,” he said.
The typical cost of a flood insurance policy is $1,100 per year, up roughly 90% in the last five years, the AP’s estimates show.
Lake Charles resident Dan Charlson said he dropped his policy when the math no longer worked. His insurance shot up over time from roughly $900 to $4,000 — an amount he expected to keep climbing.
“I’m looking at what it costs to fix the house, and the fact that I only flooded once in 50 years. So, it’s a risk analysis,” he said.
The costs have been driven up chiefly by efforts to modernize pricing.
A couple of years ago, the federal government introduced Risk Rating 2.0, a much more accurate way of aligning a property’s flood risk with the price of coverage.
But more accurately priced flood insurance meant much higher prices overall for most buyers. A government watchdog report found that Gulf Coast states had been the most underpriced and required the largest increases under the new pricing structure.
FEMA said in a statement that stronger building codes, smarter zoning and competitive private insurance options are needed rather than shifting all flood risk and cost to the federal government. Risk Rating 2.0’s accuracy gives policyholders a better sense of their true risk. The agency can’t address affordability without action from Congress, and it can’t make private insurance companies enter the market.
FEMA is working on a better system to map flood risk, called Future of Flood Risk Data. The timeline for that work isn’t clear.
Proposals to overhaul the program have stalled, including adding options to make it more affordable to low-income buyers.
“Everybody agrees it’s broken, but no one can agree how to fix it,” said Jeffrey Schlegelmilch of the National Center for Disaster Preparedness at Columbia University.
___
The Associated Press receives support from the Walton Family Foundation for coverage of water and environmental policy. The AP is solely responsible for all content. For all of AP’s environmental coverage, visit https://apnews.com/hub/climate-and-environment