A wave of student loan borrowers have entered default since pandemic-era protections lapsed
Jul 19, 2026, 9:13 PM
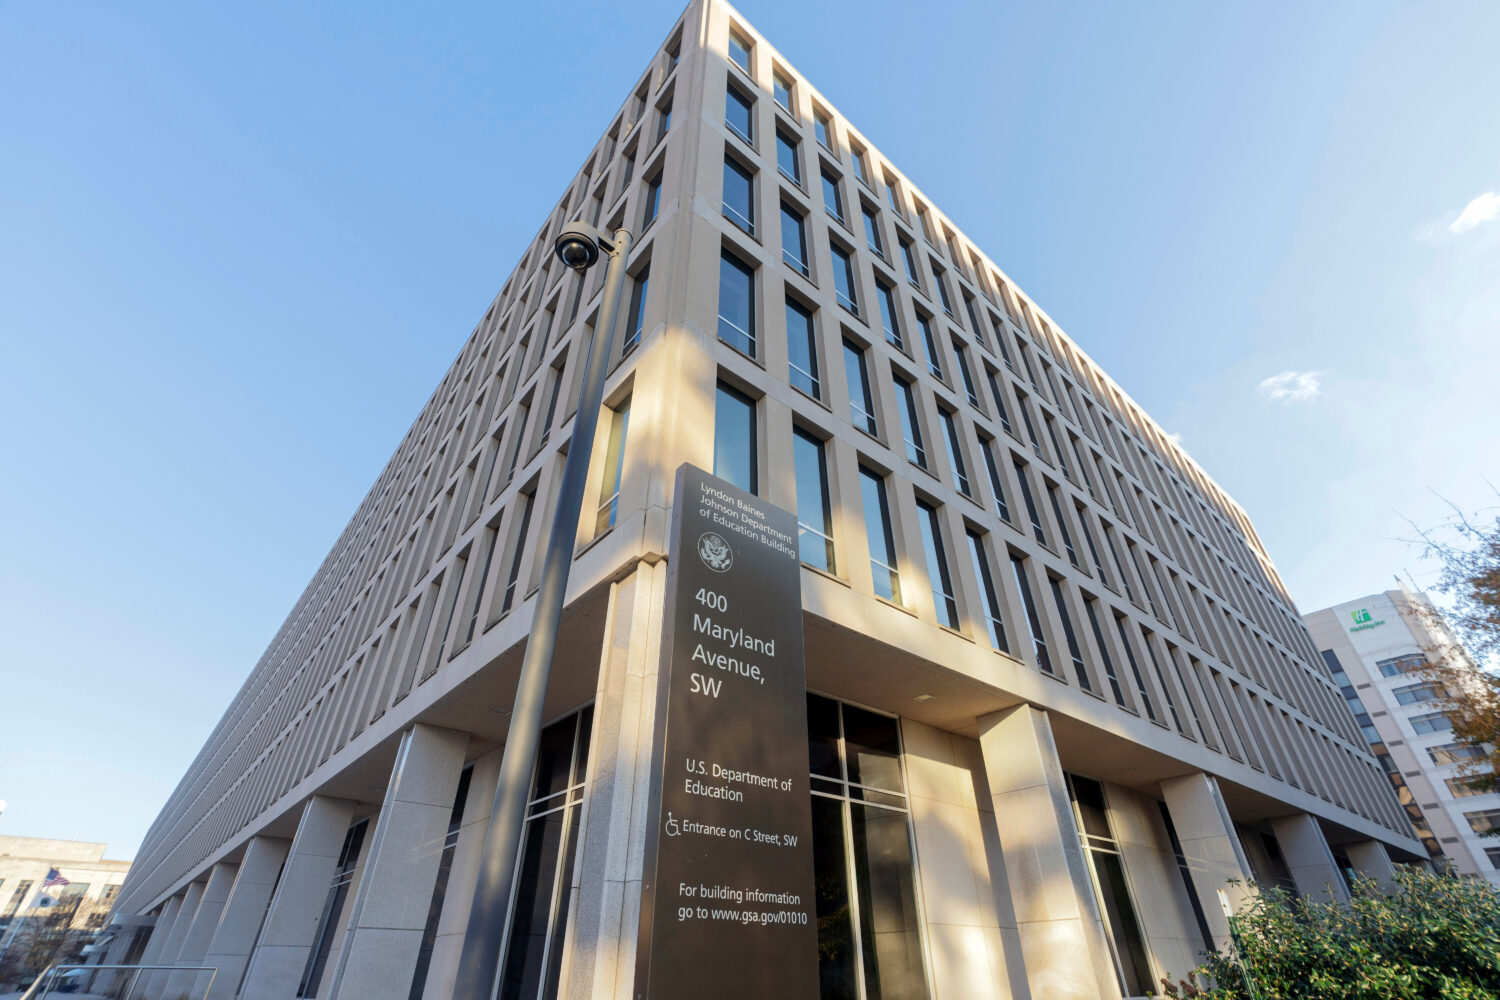
FILE - The U.S. Department of Education building is photographed in Washington, Dec. 3, 2024. (AP Photo/Jose Luis Magana, File)
Credit: AP Photo/Jose Luis Magana
(AP Photo/Jose Luis Magana, File)

Defaults on student loans have surged across the United States, reaching record levels as borrowers struggle to keep up with payments.
The numbers have spiked since payments came due again following a lengthy pause intended to provide relief during the COVID-19 pandemic. Today, around 9.5 million people — 1 in 5 federal student loan borrowers — are in default, meaning they are more than nine months behind on their payments.
While credit scores can suffer when borrowers are just a few months behind, entering default brings the possibility of more serious consequences, including garnished wages or Social Security payments. For now, the Trump administration has held off on such involuntary collections.
Despair is on the rise, advocates say.
“Folks are struggling to make ends meet and cover all the rising costs of everything else. The growing student loan bills are making things worse and folks are falling behind,” said Aissa Canchola Bañez, policy director for the advocacy group Protect Borrowers.
Here are some takeaways from an Associated Press analysis of student loan defaults.
The U.S. Education Department allowed borrowers to suspend federal student loan payments during the economic tumult of the pandemic. Though payments technically started coming due again in 2023, the Biden administration provided a one-year buffer period that ended in the fall of 2024.
Loans couldn’t enter default during this time, and federal programs designed to help delinquent borrowers and debt forgiveness initiatives brought millions out of default.
Starting in June 2025, with the pause having ended nine months prior, borrowers began defaulting again for the first time since the pandemic.
Since then, the number of defaulted borrowers has exploded from 5.3 million to around 9.5 million, according to data from the Office of Federal Student Aid. Out of $1.7 trillion in federally backed student loans nationwide, $233.3 billion is in default.
Another wave of defaults could be on the way. The Trump administration has eliminated the most generous income-driven repayment plan, Saving on a Valuable Education, or SAVE, as part of its overhaul of the federal student loan system. The millions of borrowers who had been enrolled in SAVE now will face the strain of paying more each month.
Starting this month, new borrowers pick between one standard repayment plan and one income-driven option, as opposed to having several options. The Education Department has described the changes as a simplification of a “fragmented and confusing” system.
Many of the states with the highest concentrations of defaulted borrowers are in the South, an AP analysis found.
Mississippi has the nation’s highest default rate at 28.3%, and others near the top include Louisiana, Alabama, West Virginia, Oklahoma, Georgia, South Carolina and Texas. Rounding out the 15 states with the highest default rates are Alaska, Arizona, Ohio, Indiana, Michigan, New Mexico and Nevada.
Of those states, New Mexico was the only one Republican President Donald Trump didn’t win in 2024.
“These are folks who live in states that President Trump won in the previous election,” Bañez said. “And why I bring that up is, you know, there’s a lot of misconceptions and tropes about who student loan borrowers are, and who are the ones who are falling behind.”
She said many are “working-class folks who just cannot keep up with these bills on top of everything else.”
Meanwhile, the territory of Puerto Rico had a 30.9% default rate, higher than any of the states.
Students who attended for-profit colleges struggle more than others to pay back their loans. Thirty-three percent of those borrowers were 90 days or more behind on their student loan payments, a rate more than double that of borrowers who attended public schools, according to data by the Office of Federal Student Aid released this year to help schools understand and identify default risks.
Out of the schools in the top quarter for nonpayment rates, 76% were for-profit schools.
The FSA argues that a high nonpayment rate represents a “serious risk” of developing a high default rate.
An association for private trade schools and career colleges is so concerned it has created a task force to reach out to students about the importance of loan repayment.
Jason Altmire, the head of the group, Career Education Colleges and Universities, said some of it can be chalked up to the pandemic. Other borrowers are confused over the Biden administration’s failed loan forgiveness effort. Still, he said the issue will be discussed at the association’s summer convention.
“We take it seriously,” he said. “It’s a real problem.”
___
The Associated Press’ education coverage receives financial support from multiple private foundations. AP is solely responsible for all content. Find AP’s standards for working with philanthropies, a list of supporters and funded coverage areas at AP.org.